Skip to content

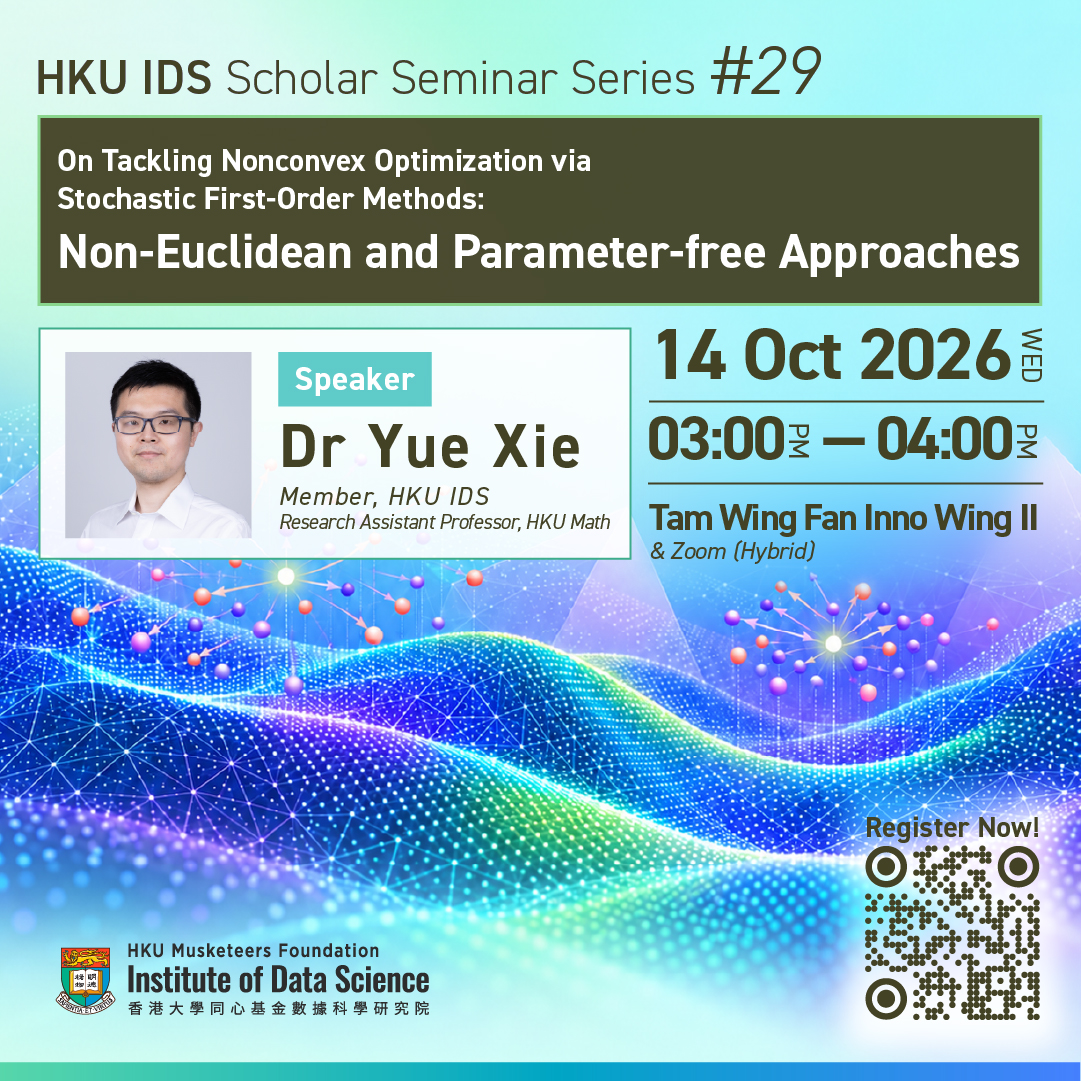
HKU IDS Scholar Seminar Series #29:

On Tackling Nonconvex Optimization via Stochastic First-Order Methods: Non-Euclidean and Parameter-free Approaches

Speaker

Dr Yue XIE
Member, HKU Musketeers Foundation Institute of Data Science
Research Assistant Professor, Department of Mathematics, HKU

Date

14 October 2026 (Wed)

Time

3:00 – 4:00 pm

Venue

Tam Wing Fan Inno Wing II |  Zoom

Mode

Hybrid. Seats for on-site participants are limited. A confirmation email will be sent to participants who have successfully registered.

Abstract

When the nonconvex problem is complicated by stochasticity, the sample complexity of stochastic first-order methods may depend linearly on the problem dimension, which is undesirable for large-scale problems. To alleviate this linear dependence, we adopt non-Euclidean settings and propose the usage of non-smooth proximal terms when taking the stochastic gradient steps. This approach leads to stronger convergence metric, incremental computational overhead, and potentially dimension-insensitive sample complexity. We also consider further acceleration through variance reduction which achieves near optimal sample complexity and, to our best knowledge, is the first such result in the l_1/l_∞ setting.


I will also present an Armijo-enabled stochastic linesearch framework with standard zeroth- and first-order oracles. The resulting steplength sequence is non-monotone and requires neither knowledge of Lipschitz smoothness constant L nor any other problem parameters – hence (problem-)parameter-free. The proposed method allows for a simple nonsmooth convex component in the objective, addressed through proximal gradient updates. Analogous guarantees are provided in the Polyak-Łojasiewicz (PL) setting and convex regimes. Preliminary numerical experiments are seen to be promising.

Publication Note

This seminar is based on Prof Qingpeng ZHANG’s recent publication in PNAS, with Dr Fei JING—his Postdoctoral Fellow at IDS—as first author. Prof ZHANG will give a detailed account of the paper and its theoretical framework for understanding the predictability limits of complex systems.

Speaker

Dr Yue XIE

Member, HKU Musketeers Foundation Institute of Data Science
Research Assistant Professor, Department of Mathematics, HKU

Dr Yue Xie is a Member of the HKU Musketeers Foundation Institute of Data Science and a Research Assistant Professor at the Department of Mathematics, HKU. He was a postdoc at UW Madison working in the nonconvex optimization group led by Professor Stephen J. Wright. He received his PhD degree in Pennsylvania State University and Bachelor degree from Tsinghua University. Dr Yue Xie has been focusing on algorithm design and analysis to address nonconvex and stochastic optimization problems with all types of applications including machine learning and data science. He has published/served as the referee of top-tier journals including Mathematical Programming, SIAM Journal on Optimization, and IEEE Transactions on Automatic Control, etc. He has delivered numerous presentations at major international conferences such as International Conference on Continuous Optimization (ICCOPT), International Symposium on Mathematical Programming (ISMP), SIAM Conference on Optimization and International Conference on Machine Learning (ICML).

More details about him can be found at: https://yue-xie.github.io./
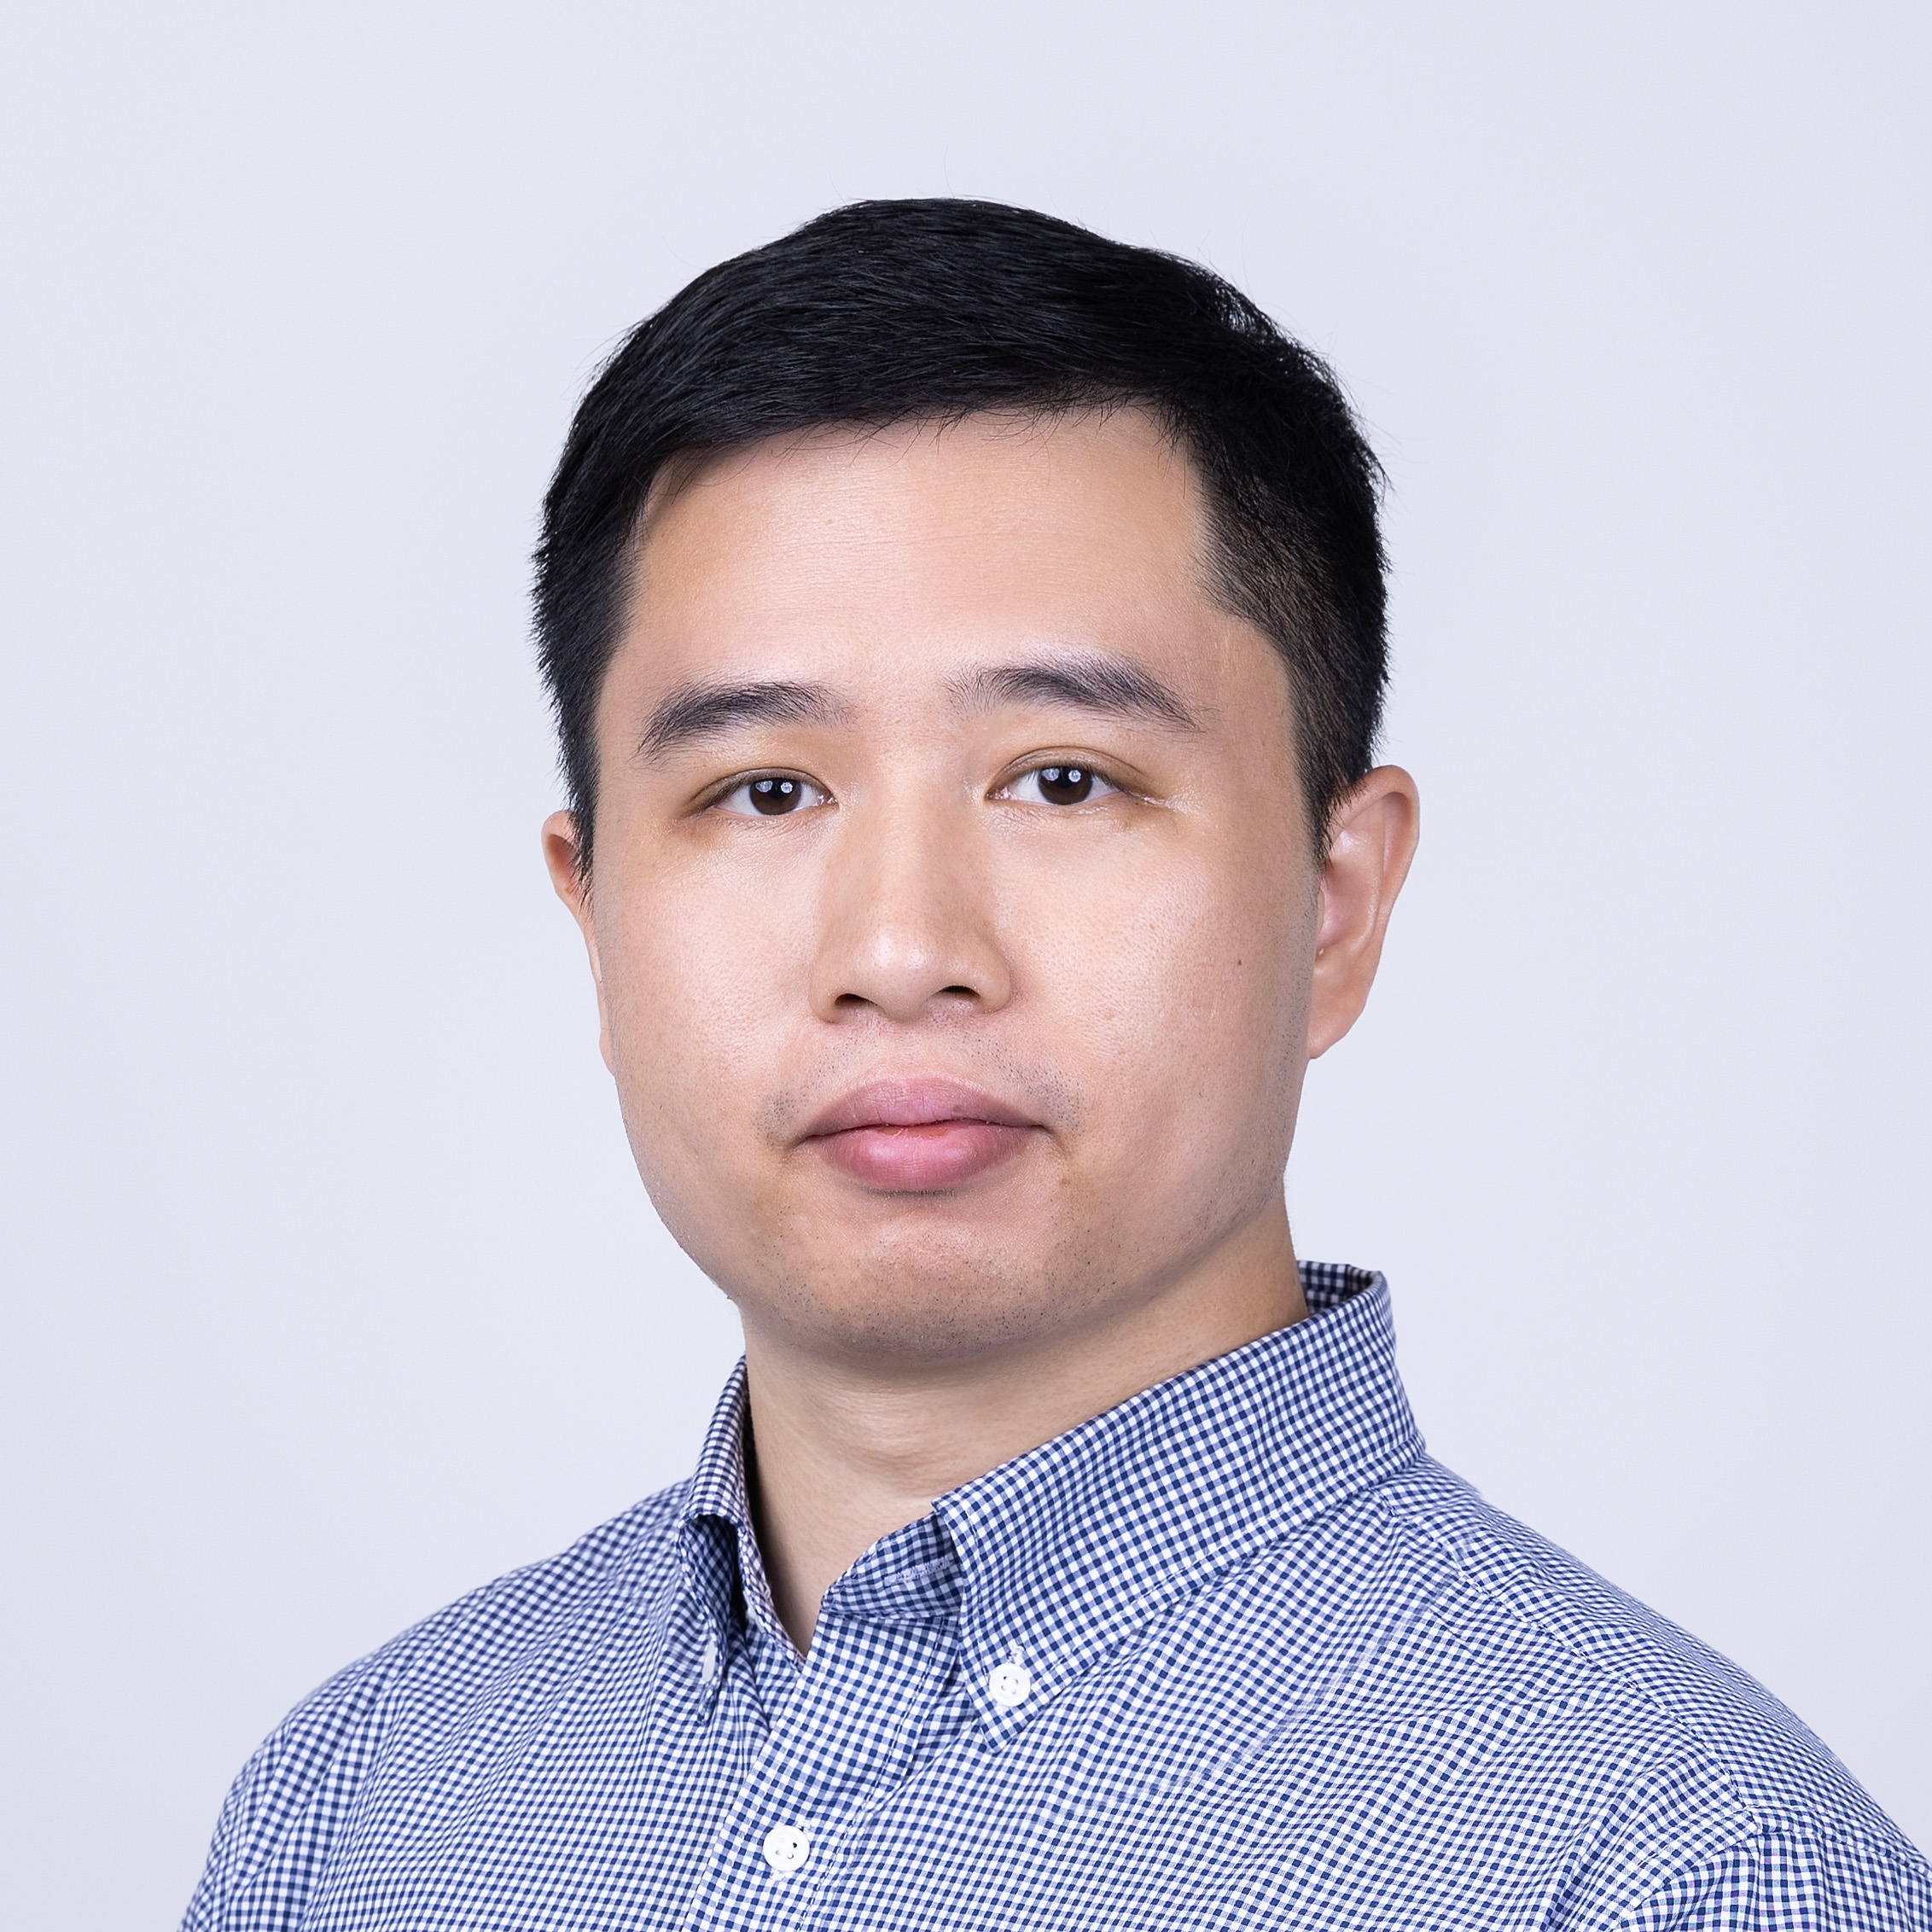
Moderator

Prof Difan ZOU

Member, HKU Musketeers Foundation Institute of Data Science
Assistant Professor, Department of Computer Science, HKU School of Computing and Data Science

Prof Difan Zou is a Member of the HKU Musketeers Foundation Institute of Data Science and an Assistant Professor at the HKU School of Computing and Data Science. He received his Ph.D. in Computer Science, University of California, Los Angeles (UCLA). He received a B. S degree in Applied Physics, from School of Gifted Young, USTC and a M. S degree in Electrical Engineering from USTC. He has published multiple papers on top-tier machine learning conferences including ICML, NeurIPS, ICLR, COLT, etc. He is a recipient of Bloomberg Data Science Ph.D. fellowship. His research interests are broadly in machine learning, optimization, and learning structured data (e.g., time-series or graph data), with a focus on theoretical understanding of the optimization and generalization in deep learning problems.

For information, please contact:
Email: datascience@hku.hk